

EveryDollar: Budget Management
by Ramsey Solutions
4.3
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.3
- Price
- Free
- Download
- 1.00M
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
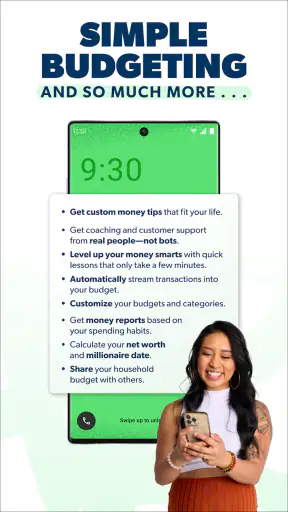
 Analysis by Getfullapps
Managing money becomes much easier when every dollar already has a job before the month gets busy. That is the idea I kept coming back to while using EveryDollar, a finance app from Ramsey Solutions that focuses on planning spending rather than merely recording it afterward. It is free to install, rated for Everyone, and available for Android devices running version 7.0 or later. Its average rating sits at 4.3 from around 15 thousand ratings, and more than a million people have installed it, so it is clearly aimed at ordinary households rather than specialist finance users.
What makes this app interesting is its emphasis on a zero-based budget: income is assigned across bills, everyday spending, savings, and other priorities until there is no unplanned money left floating around. That sounds simple, but it changes the question from “Where did my money go?” to “What is this money supposed to do?” In my experience, that shift is the app’s real strength. It encourages a decision before spending, not just an explanation afterward.
Giving every dollar a clear job
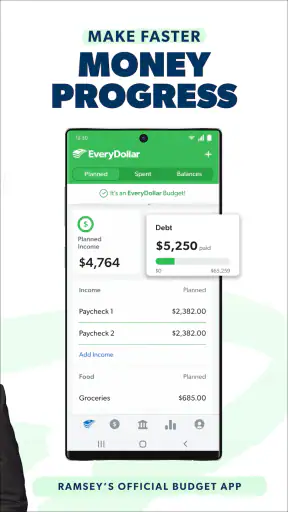
The central capability is the monthly budget plan. Instead of opening the app only after a purchase, I found it more useful to begin with expected income and then create categories for the obligations and goals that matter during that month. Rent, groceries, transport, subscriptions, debt payments, and savings can each be treated as separate destinations for the available money.
This approach is especially helpful for people whose spending feels scattered across many small decisions. A coffee, a fuel stop, or an unplanned takeaway may not look serious alone, but a category-based plan makes the combined effect visible. The app gives those purchases a place in the wider month, which makes it easier to notice when a harmless-looking habit is taking money away from something more important.
I also like that the method encourages planning irregular expenses instead of pretending they do not exist. Annual renewals, school costs, gifts, car maintenance, and seasonal spending can be considered before they arrive. Even if the amount set aside is modest, the act of recognizing the expense removes some of the surprise. This is one of the less obvious benefits of the system: it turns occasional costs into regular planning decisions.
The app is not simply a digital notebook for transactions. Its value depends on the discipline of assigning money deliberately. If I enter a budget and never return to update it, the plan quickly becomes an optimistic snapshot rather than a useful guide. The strongest results come from treating it as a short check-in tool throughout the month.
Why the planning method feels different
Many banking apps show balances and spending charts. Those views are useful, but they are usually retrospective. They tell me what happened. EveryDollar is more forward-looking: it asks me to decide how available income should be used and then compare real spending with that decision.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
That distinction matters when the bank balance looks healthy but several bills are still waiting. A balance alone can make money appear available when it is already committed. A category plan gives that balance context. I can see that part of it belongs to groceries, part to an upcoming payment, and part to a goal, rather than treating the entire amount as spendable.
There is also a psychological advantage. A broad instruction such as “spend less” is difficult to follow because it does not define what success looks like. A category limit is more concrete. If the food budget is nearly used, I have a practical choice: slow down, move money from another category, or accept that the original plan needs changing. None of those choices is automatic, but the app makes the decision visible.
How I would use it during a normal month
I would start by entering the income I reasonably expect and listing fixed commitments first. This prevents flexible spending from taking priority over bills. Next, I would estimate variable costs using recent habits rather than idealized hopes. A budget that assumes I will suddenly stop buying convenience food is less useful than one that reflects reality and shows me where a gradual change could help.
After that, I would allocate money to less frequent expenses. This is where the method can reveal a problem that a normal spending tracker may hide. If a yearly bill is due soon and nothing has been reserved for it, the issue is not necessarily excessive daily spending; it may be that the expense was never included in the plan. Recognizing that early gives me more options than discovering it on the due date.
During the month, I would record purchases as they happen and compare them with the category amounts. The practical tip here is to update the budget soon after spending, while the reason for the purchase is still clear. Waiting until several days have passed makes small transactions easier to forget and can create a false sense that there is more room left than there really is.
When a category goes over its planned amount, I would not treat that as a reason to abandon the whole budget. I would move money from a category that can absorb the change, then continue. This is an important trade-off: the plan is meant to guide decisions, not punish imperfect months. A budget that can be adjusted honestly is more valuable than one that looks perfect only because spending was left unrecorded.
One useful workflow is to separate “planned” from “available.” Suppose I receive income near the start of the month and have several bills due later. I can assign those funds immediately instead of waiting for each payment to approach. That reduces the temptation to interpret the current bank balance as spare cash. For households paid on different schedules, this forward planning can also make the month feel less chaotic, although it requires careful income timing.
A realistic household example
Imagine I am paid twice during the month and the first payment arrives before the largest bills. Without a plan, the account balance may look comfortable for a few days. I might spend freely, only to feel squeezed when rent and utilities are due. With EveryDollar, I would assign the first payment to the obligations that must be covered, then reserve what remains for food, transport, and near-term priorities.
If groceries cost more than expected in the first week, I would see the effect in that category instead of discovering it at the end of the month. I might reduce restaurant spending, delay a nonessential purchase, or revise the grocery allocation. The important point is not that the app prevents overspending. It does not. Its benefit is that it makes the consequence of each choice easier to understand while there is still time to respond.
For a couple, the category structure can also provide a shared vocabulary. Rather than arguing about whether one person “spends too much,” both people can look at the same planned amount and discuss the trade-off. That does not remove disagreements, but it moves the conversation away from memory and toward a visible plan.
The trade-offs behind the simple interface
The simplicity is both the app’s advantage and its limitation. Someone who wants a focused budgeting routine may appreciate the uncluttered approach. Someone who expects a full financial dashboard, detailed investment analysis, or sophisticated forecasting may find it narrow. This is primarily a budgeting tool, not a replacement for every financial service a person might use.
It also asks for regular attention. The method works best when I record spending, review categories, and make adjustments instead of assuming the first plan will survive unchanged. That can feel like extra work compared with opening a banking app and glancing at a balance. The trade-off is that the extra attention produces more intentional decisions.
Another friction point is the difference between a budget and a bank account. A budget can tell me what money is assigned to groceries, but it does not make the money physically separate. I still need to understand which funds are in the account, which payments are pending, and when income will arrive. Anyone who treats the category totals as a substitute for checking real account activity may become overconfident.
The free version makes the basic budgeting idea accessible, which is important for someone testing whether this style suits them. The app also includes in-app purchase options ranging from $7.99 to $129.99 per item. I would not pay for extras until the basic routine had become useful on its own. The key question is not whether more tools sound appealing; it is whether they solve a specific problem in my household.
Privacy and comfort are also personal considerations whenever financial information is entered into an app. I would begin with the minimum information needed for my chosen workflow and make sure I understood how I wanted to handle account details before building a complete financial routine around it. For someone uncomfortable with digital budgeting, a paper envelope system may feel more natural and provide the same behavioral lesson without an app.
Where alternatives may be better
A spreadsheet can be a better choice for a person who wants complete control over formulas, custom reports, or unusual income patterns. It takes more setup, but it can be shaped around almost any household. A bank’s own budgeting view may be more convenient for someone who wants spending information in the same place as account activity. That convenience can matter more than EveryDollar’s planning focus if the user rarely wants to make a detailed plan in advance.
On the other hand, a general expense tracker may be less demanding but also less motivating. Tracking tells me what happened; EveryDollar’s category allocation asks me to make a choice before the money disappears. For a beginner who needs a clear starting structure, that stronger planning emphasis is likely to be more useful than a collection of charts.
I would skip it if I dislike category-based budgeting, have highly unpredictable finances that make monthly planning feel misleading, or want investment and net-worth tools in the same experience. It may also be a poor fit for someone unwilling to update purchases consistently. No budgeting app can create accuracy from neglected entries.
Who gets the most from this approach
I think the best audience is someone who earns enough to cover regular needs but still feels unsure where the money goes. The app is also well suited to people starting a debt-payoff or savings habit, because assigning money in advance makes competing priorities easier to see. A household preparing for an irregular bill can benefit too, especially if surprise expenses repeatedly disrupt otherwise manageable months.
Beginners may appreciate the clear structure, while experienced budgeters can use it as a straightforward monthly reset. The method is particularly valuable for people who tend to confuse account balance with available money. Seeing funds assigned to specific purposes can create a useful pause before an impulse purchase.
It is less suitable for someone seeking passive automation. EveryDollar is most effective when I participate in the process: I decide the categories, enter or review spending, and adjust the plan when life changes. That involvement is not a flaw for a person who wants to learn financial habits, but it is a real commitment for someone who wants everything handled in the background.
The app’s Everyone rating makes it approachable for a broad audience, and the current version is 2026.8.240. Ramsey Solutions has positioned it as more than a simple spending log, and I think that description is fair when the user actually follows the planning method. The value comes from the behavior it encourages, not from merely having it installed.
My final view after using the budgeting method
EveryDollar is a focused finance app with one strong idea: decide what income should do before everyday spending decides for you. I found that approach more useful than a passive list of transactions because it connected small purchases with larger goals and upcoming obligations.
Its weaknesses are equally clear. It requires regular input, it does not replace awareness of real bank balances, and it may feel too limited for users wanting a complete financial command center. The optional in-app purchases also mean I would start with the free experience and judge the routine before spending anything.
If you want a practical monthly plan and are willing to check in consistently, this is a worthwhile place to start. If you only want automatic reports or advanced financial analysis, a bank tool, spreadsheet, or broader money-management service may suit you better. For me, the app succeeds because it turns budgeting from a vague intention into a series of specific decisions I can make before the month gets away from me.
Pros
- Simple zero-based budgeting makes spending plans easy to understand.
- Quick expense entry helps users keep their budget updated on the go.
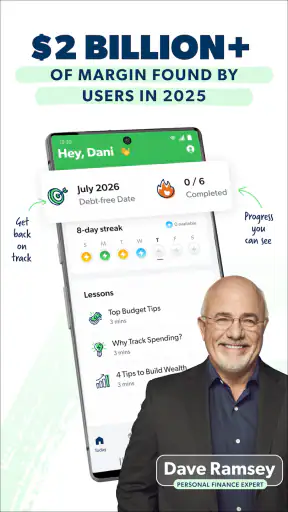
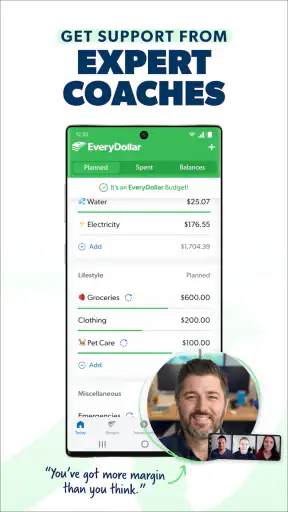
- Clear monthly overview shows planned, spent, and remaining amounts.
- Syncing across devices keeps budget information accessible wherever you are.
- Useful for households that want a straightforward, focused budgeting system.
Cons
- Many useful features require the paid Premium subscription.
- Bank connections may occasionally need reconnecting or manual updates.
- Limited investment and debt-management tools compared with broader finance apps.
- Manual entry can become time-consuming for users with many daily transactions.
- Some users may find zero-based budgeting restrictive for irregular income.
FAQs for EveryDollar: Budget Management
What is EveryDollar: Budget Management, and how does it work?
EveryDollar is a budgeting app designed around zero-based budgeting, where you assign your expected income to specific spending, saving, and debt categories until every dollar has a purpose. You can create monthly budgets, record transactions, monitor category balances, and review your progress. Its straightforward layout makes it useful for people who want a structured plan rather than simply tracking expenses after they occur.
Is EveryDollar free to download and use?
EveryDollar can generally be downloaded at no cost, and its basic budgeting features may be available through a free version. However, some advanced tools require a paid subscription, depending on the current plan and region. Premium features may include automatic transaction importing, additional budgeting conveniences, and enhanced account functionality. Check the in-app pricing and subscription terms before starting a trial or purchase.
Does EveryDollar connect to bank accounts automatically?
Automatic bank connection is typically associated with EveryDollar’s premium features, while the free experience usually relies on manually entering transactions. When bank syncing is available, imported transactions can reduce data-entry work, but users should still review them for accuracy and categorize them correctly. Bank compatibility, connection availability, and supported institutions can vary, so confirm that your financial institution is supported.
Is EveryDollar safe for managing personal financial information?
EveryDollar is built to handle budgeting information and may use security measures such as encrypted connections and account authentication to help protect user data. Nevertheless, no online financial service is completely risk-free. Use a strong, unique password, enable available security options, avoid sharing login details, and keep your device updated. Review the app’s privacy policy to understand how personal and financial information is handled.
Who should use EveryDollar, and what are its main limitations?
EveryDollar is a good fit for users who prefer intentional, category-based budgeting and want to plan spending before the month begins. It can also help households discuss shared financial goals and track progress toward savings or debt repayment. Its main limitations may include subscription costs for advanced features, manual entry in the free version, and the discipline required to maintain accurate categories and transaction records.

EveryDollar: Budget Management
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via help@everydollar.com, visit https://everydollar.com/, or review their https://www.everydollar.com/privacy/plain.










